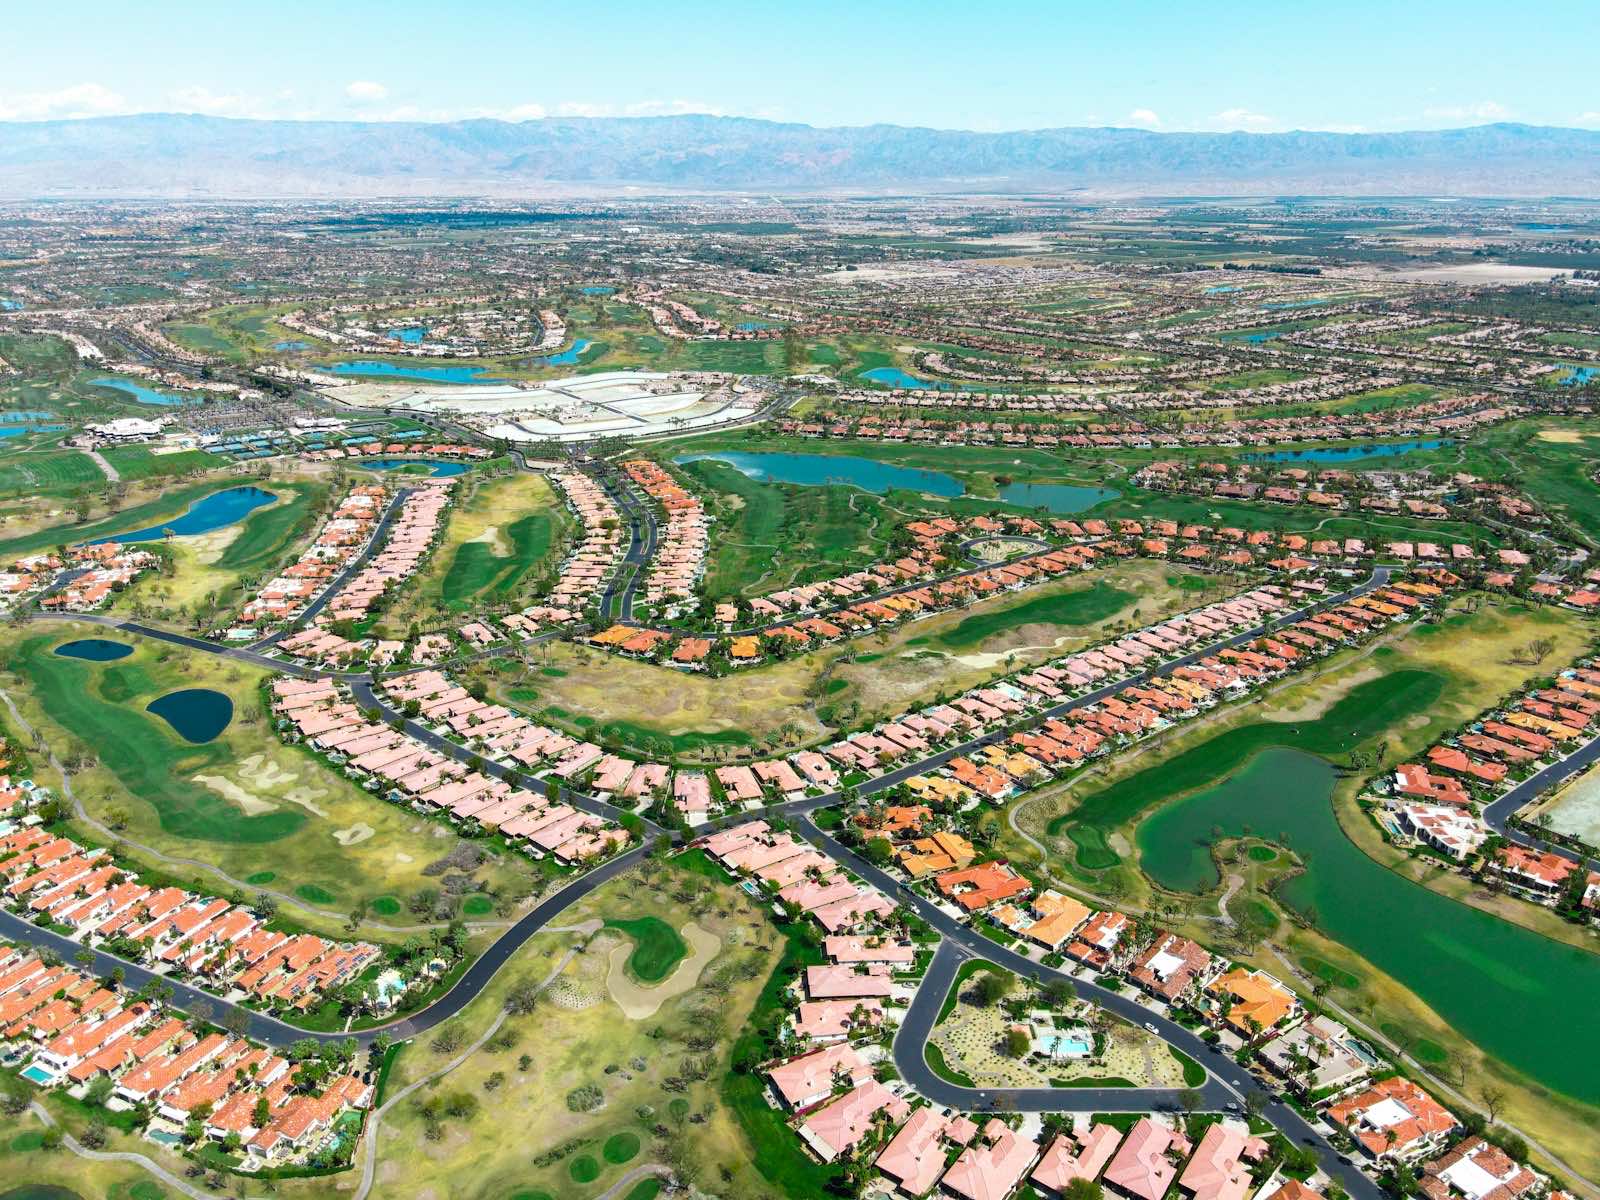
"Golf ball broke my window" is the first thing a resident says to the board after a stray shot comes through the glass. In Florida it lands on condo and HOA directors in golf course communities, usually before anyone has opened the declaration.
This month it was a Lake Worth condominium on the news. The answer to "who pays" is not one rule. It lives in four places, read in order: the recorded documents, the insurance split, the course's own agreements, and what the board does next.
What CBS12 reported from Lake Worth
CBS12 reporter Tiffany Rizzo reported on October 13, 2026 on Barclay at Poinciana, a Lake Worth condominium next to Poinciana Golf Club. Resident Teresa Scheil told the station, "This is my unit, and this will be the second time we've replaced this window." CBS12 also reported holes punched in fences.
Resident Shannon Gallagher told CBS12 she was in her garden when "a ball hit me in the forehead, leaving me this lovely dent in my head." Gallagher also said, "I think it's a newer problem since they moved the tees."
Course manager Ken Muro told CBS12, "We get calls not often, but often enough." He added, "We feel terrible, it's unfortunate, but it is part of being on a golf course." On warning buyers, Muro said, "It should be told to them probably by whether it be the HOA or the realtor."
Attorney Michael Gelfand told CBS12, "The golf course owner might be held for negligence or for a nuisance. But most golf course owners have covenants that protect them from claims." On the moved tees, Gelfand put the question this way: "does the tee create a danger for others?" He also said, "Folks sign their contracts and they go to closings without understanding what's in all that paper they've been given."
That last line is the whole point. The paper decides, so the board reads the paper first.
Step 1: read the declaration and the recorded covenants first
Before anyone calls the insurance agent or the golfer, pull the recorded declaration, every amendment, the plat, and any recorded easement that mentions the course. Golf course communities are often built with a clause that shifts the risk of errant balls onto the people who buy next to the fairway.
What does such a clause look like? FindLaw's Florida overview of golf ball hazards, last updated June 20, 2016, gives a sample. It is a legal publisher's explainer, not law, and it is quoted here only to show the shape of the language.
The sample easement says each lot "is burdened with an easement permitting golf balls hit from the Club facilities to unintentionally come upon the Lot." It also lets golfers "come upon the exterior portions of the Lot to retrieve errant golf balls." The sample risk clause says owners "assume all risks associated with errant golf balls." In it, owners agree not to sue the developer, the club, the course designer or the builder. The one party left open is "the golfer who caused the property damage or personal injury."
So the board is looking for three things:
- An easement that lets balls land on the property and lets golfers come onto it.
- An assumption of risk clause, and the list of parties it protects. Note whether it names the association itself.
- Any carve-out that leaves the golfer, and only the golfer, open to a claim.
Attorney Astrid Guardado of Becker & Poliakoff wrote on September 25, 2018 that "Community associations are not automatically insulated from liability regarding errant golf balls." Her recommendation: the governing documents and marketing materials "should clearly provide that the association cannot be held liable for any damage or injury caused by golf balls." That is one firm's view, not law.
Section 718.111(12)(a), Florida Statutes (2026), lists the recorded declaration, the recorded bylaws, the articles, and "All current insurance policies of the association" among a condominium's official records. Section 718.111(12)(c)1. says the official records "are open to inspection by any association member." Records must be provided "within 10 working days" of a written request. A failure to do so creates "a rebuttable presumption that the association willfully failed" to comply.
For homeowners' associations, section 720.303(4), Florida Statutes (2026), requires the association to keep "A copy of the declaration of covenants and a copy of each amendment thereto." The same list includes "All of the association's insurance policies or a copy thereof" and "A current copy of all contracts to which the association is a party." Section 720.303(5)(a) says those records go to a parcel owner "within 10 business days after receipt by the board or its designee of a written request."
Step 2: who pays when a golf ball broke my window in a condo
Section 718.111(11)(f), Florida Statutes (2026), says the association's property policy must cover "All portions of the condominium property as originally installed or replacement of like kind and quality." It must also cover "All alterations or additions made to the condominium property or association property."
The same paragraph then lists what the master policy "must exclude." Every item on that list has to be "located within the boundaries of the unit and serve only such unit." The list reads:
- "all personal property within the unit or limited common elements."
- "floor, wall, and ceiling coverings, electrical fixtures, appliances, water heaters, water filters, built-in cabinets and countertops."
- "window treatments, including curtains, drapes, blinds, hardware, and similar window treatment components."
Read that list closely. The words "window" and "door" do not appear anywhere in paragraph (11)(f). "Window treatments" do, and they are excluded. So under the statute's default, a window installed as part of the original building sits on the association's side of the coverage list. The curtains and blinds hanging inside it sit on the owner's side.
Two cautions before anyone writes a check. First, the declaration can allocate repair differently, and the statute says so. Section 718.111(11)(j) covers the case with no insurable event. Then "the association or the unit owners shall be responsible for the reconstruction, repair, or replacement as determined by the maintenance provisions of the declaration or bylaws." Many declarations assign windows and sliding glass doors to the unit owner for maintenance and replacement. Second, whether a golf ball strike is an insurable event under your association's policy is a question for the policy and your agent.
Then the deductible. Section 718.111(11)(j) says property insurance deductibles "are a common expense of the condominium, except that" the unit owner pays in one situation. The exception covers damage "caused by intentional conduct, negligence, or failure to comply with the terms of the declaration or the rules of the association." The statute applies it to the unit owner, family members, occupants, tenants, guests, and invitees. A stranger on the course next door is not on that list. One broken window usually costs less than a property deductible, so the deductible rule is the one that matters. We covered how the deductible works after a storm in our post on the condo master policy and the hurricane deductible after Isaias.
One more line matters. Section 718.111(11)(k) says an association may "opt out of the provisions of paragraph (j)" with "the approval of a majority of the total voting interests in the association."
Step 3: in an HOA, the house is the owner's
In a homeowners' association the lot and the house on it belong to the owner, not the association. So the owner's homeowner policy is the first call. FindLaw's explainer says it in plain words: "Although golfers may be responsible for damage, collecting can be difficult and impractical. Instead, many homeowners choose to purchase homeowner's insurance to cover such an event."
The HOA board still has a role. Section 720.303(4) makes the declaration of covenants, the insurance policies, and the contracts official records, so the board holds the papers that answer the question. Fences and walls along the course may be association property, depending on the plat and the declaration.
Step 4: the golf course and its agreements with the community
The course is usually a separate owner. The community may hold a written agreement with it about buffers, screens, netting, or tee placement. If the association signed such a contract, section 720.303(4) makes it an official record an owner can ask to see.
Gelfand's framing, "does the tee create a danger for others?", is the question a board should put to the course in writing, with the incident log attached. Whether a covenant protects the course in a given dispute depends on what the recorded documents say. That is why Step 1 comes first.
What the board can do now
- Document every incident. Date, time, unit, the hole or tee if known, photos, the repair invoice, and any injury.
- Read the documents with counsel. The declaration and amendments, the plat, any recorded easement, any agreement with the course, the master policy, and the unit boundary definition. Ask counsel one plain question: under our documents, who repairs this window, and who pays the deductible?
- Talk to the course. Netting, screens, tree lines, and tee placement are the course's tools. Muro told CBS12 the course can "only do so much," so put the request and the incident count in writing.
- Tell buyers. Muro said the warning should come from "the HOA or the realtor." A board can add a short written notice to the documents it hands to buyers.
- Tell owners what their own policy must do. Under section 718.111(11)(f), personal property and window treatments inside the unit are the owner's to insure.
Our condominium management team keeps the declaration, the policies, and the incident log together so a board can answer this question in a day, not a season. If your board is reading its declaration for the first time after a broken window, contact us. We will help you gather the documents before the meeting with counsel.
This article reports what the documents and the statutes say. It does not advise on any claim. Before anyone pays or denies one, confirm with association counsel and your insurance agent.
Frequently asked questions
Does the condo master policy cover a window broken by a golf ball?
Section 718.111(11)(f), Florida Statutes (2026), requires the master policy to cover "All portions of the condominium property as originally installed." Its exclusion list names window treatments, not windows. Whether a golf ball strike is an insurable event depends on the policy, and the declaration may assign window repair to the owner.
Who pays the deductible when a golf ball breaks a condo window?
Section 718.111(11)(j) makes property insurance deductibles "a common expense of the condominium." The exception is damage caused by the intentional conduct, negligence, or rule violation of a unit owner, family member, occupant, tenant, guest, or invitee. Section 718.111(11)(k) lets an association opt out by a majority of the total voting interests.
What is a golf ball easement?
It is a recorded clause, common in golf course communities. It lets balls from the course land on the lots and lets golfers come onto exterior areas to retrieve them. FindLaw's sample language pairs it with a clause in which owners "assume all risks associated with errant golf balls."
Can an owner get a copy of the declaration and the insurance policy?
Yes. Section 718.111(12)(a) lists the recorded declaration and all current insurance policies as official records. Section 718.111(12)(c)1. says they must be provided within 10 working days of a written request. For HOAs, section 720.303(4) and (5)(a) set the same kind of rule, with a 10 business day clock.
Does the golf course have to pay for stray golf ball damage?
Not automatically. Attorney Michael Gelfand told CBS12 a course owner "might be held for negligence or for a nuisance." He added that "most golf course owners have covenants that protect them from claims." Whether a covenant applies depends on the recorded documents and the facts, which is a question for association counsel.
Sources
- Tiffany Rizzo, "Broken windows, flying golf balls: Lake Worth neighbors talk risks living on golf course," CBS12, October 13, 2026. cbs12.com
- Section 718.111, Florida Statutes (2026), subsections (11)(f), (11)(j), (11)(k), (12)(a), and (12)(c). The Florida Senate. flsenate.gov
- Section 720.303, Florida Statutes (2026), subsections (4) and (5)(a). The Florida Senate. flsenate.gov
- FindLaw, "Golf Ball Hazards in Florida: Legal Overview," last updated June 20, 2016 (interpretive explainer with sample covenant language). findlaw.com
- Astrid Guardado, Esq., Becker & Poliakoff, "Those Pesky Little White Balls," Florida Condo & HOA Law Blog, September 25, 2018 (interpretive, one law firm's view). floridacondohoalawblog.com